I=5
Buy, $886: Rosenblatt said the subscription ramp appears faster than Snap, which reported over 25 million subscribers and a $1 billion annual recurring revenue early this year for its Snapchat+ subscription, a little over 3.5 years after launch. It also pointed out that Muse AI agent continues to rank near the top of app store rankings since its September 8 launch, adding to the company’s recent momentum.
I=5
BMO Capital Markets views global age verification push as early stage risk for Meta
BMO said the structural changes from the recent youth settlement are more punitive than the financial costs, warning that the settlement could prompt U.S. lawmakers to impose further restrictions on minors’ social media use and sustain regulatory pressure on Meta and its peers. It pointed out that age verification requirements remain in early stages following Australia’s implementation of online age verification rules in December 2025 and that multiple countries have since introduced similar laws restricting minors’ access to online content.
I=4
Buy, $800: Citi analyst Ronald Josey opened an “upside 90-day catalyst watch” on Meta Platforms. He expects Meta to provide clarity on its product strategy during its September 23 Connect event. Josey also expects the product roadmap to provide multiple catalysts ahead, which should drive better engagement and monetization over time.
I=5
Buy, $810: BofA Securities said custom chips remain a key part of Meta’s AI strategy, with the potential to materially reduce long-term infrastructure costs and improve returns on AI capex, citing Alphabet’s success with TPUs as a precedent.
I=4
Dan Ives, Partner and Senior Managing Director at Yorkville said Meta is unlikely to slow down its AI push.
“When you get to the top of, you know, the penthouse, you don’t stop the elevator to others coming up, and I think the regulatory capture issue, you’ve seen the industry push back hard,” Ives said. “Instead, they’re going to be in a Ferrari left lane going 100 miles an hour because that just enables them to narrow the gap,” Ives said.
“It’s those with the install bases that are going to be able to monetize,” he said.
I=6
Overweight, $640->$796: Wells Fargo said it believes Meta now has a story to tell heading into Meta Connect conference. Analyst Ken Gawrelski pointed to an unprecedented download and active user trajectory for Meta’s Muse during its first 12 days in the U.S. According to SensorTower data, Muse recorded 264,000 U.S. downloads on September 19, its third consecutive day above 200,000, while daily active users reached 448,000 just 10 days after launch, compared with ChatGPT, which took nearly a year to surpass 200,000 daily U.S. downloads and 49 days to reach 450,000 DAUs.
I=5
Buy, $710->$875: Jefferies said Meta’s Muse has “all the hallmarks of a killer app,” citing exceptional consumer adoption that significantly exceeds Anthropic’s Claude and Google’s Gemini, alongside substantial monetization potential.
Jefferies pointed out that if Muse reaches 1 billion users by end of 2027 and around 3% transition to a paid version then it could result in $10.8 billion in annualized revenue.
I=5
Buy, $810: Bofa analyst Justin Post said early reviews suggest Muse’s functionality is resonating with users. It pointed out that early reviews from the WIRED and Business Insider highlighted Muse’s ability to execute multi-step tasks and workflows with limited user intervention, including effective web-browsing capabilities and email prioritization features. TechRadar praised Muse’s usefulness but highlighted concerns about giving the agent extensive access to personal data, while BofA identified privacy and trust as key hurdles to broader adoption.
I=5
Outperform, $750: Mizuho analyst Lloyd Walmsley said Meta’s bull case is increasingly playing out, pointing to rapid adoption of its Muse AI agent ahead of the company’s Connect event. He said Meta’s Connector Platform, opened to third-party developers on Sept. 18, could pave the way for transaction-based monetization, potentially allowing Meta to charge businesses a fee for reaching Muse users. He added that Shopify has enabled checkout within Muse, joining Stripe, while Amazon has blocked Muse, which Walmsley said validates its growing scale. The analyst noted that Mark Zuckerberg has indicated Meta could eventually capture a share of the value generated by Muse, potentially disrupting Google Search, online travel agencies and e-commerce advertising.
I=4
Overweight, $820: JPMorgan cited the combination of virality and Meta’s distribution platform as factors driving momentum around Muse.
I=5
Buy, $860: Evercore ISI’s Mark Mahaney called Muse the best product coming to market. He praised Muse’s intuitive ability. Mahaney pointed out that Meta could generate ad and transaction revenue from it.
I=4
-
Overweight, $780->$900: KeyBanc said Meta Muse’s strong momentum supports its view that sentiment toward consumer AI is set to improve, while highlighting Meta’s multiple opportunities to generate additional revenue growth. The firm raised Meta’s 2027 revenue forecast to $313.8 billion, representing 23% year-over-year growth, and its 2028 revenue forecast to $378.7 billion, representing 21% growth. Its EPS forecast now stands at $35.09 for 2027, approximately 4% above Street estimates, and $40.50 for 2028, 1% above Street estimates.
-
Overweight, $680->$860: Cantor Fitzgerald said personal AI agents could become a major development in artificial intelligence, with Meta well positioned to capitalize on the trend through a competitive model designed for agentic tasks.
“We believe the unit economics of Muse are being subsidized in the early days, but we think META has several paths to a profitable freemium model.”
I=5
Analysts grow more bullish on Meta following Connect event
-
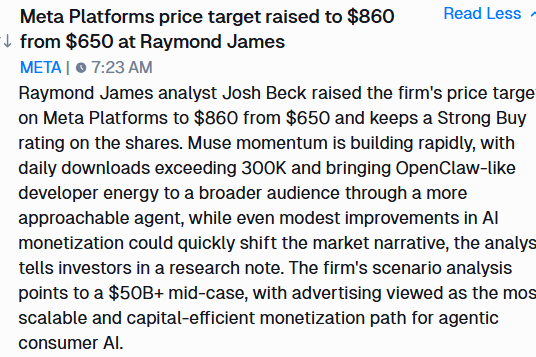
Strong buy, $650->$860: Raymond James analyst Josh Beck said Muse momentum is rising rapidly. His scenario analysis suggests a mid-case opportunity exceeding $50 billion, with advertising seen as the most scalable and capital-efficient way to monetize consumer AI agents.
-
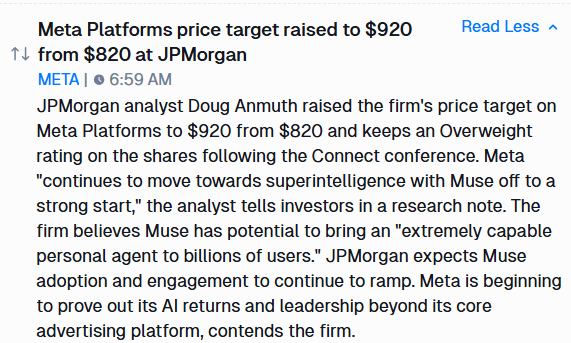
Overweight, $820->$920: JPMorgan analyst Doug Anmuth said Muse is off to a strong start and Meta is beginning to demonstrate tangible returns and leadership from its AI investments beyond its core advertising business.
-
Outperform, $770->$885: Citizens Financials said Meta Connect 2026 highlighted an increasingly AI-first hardware ecosystem as Muse momentum continues.
-
Outperform, $750: Mizuho said Meta Connect 2026 reinforced Muse as a core part of Meta’s AI and hardware strategy, spanning AR glasses and the upcoming Muse Charm device. The firm highlighted Muse’s rapid rise to the top of the iOS App Store, growing promotion across Meta’s platforms and increasing third-party connector adoption, arguing that the product’s strong momentum could support multiple expansion for Meta shares.
-
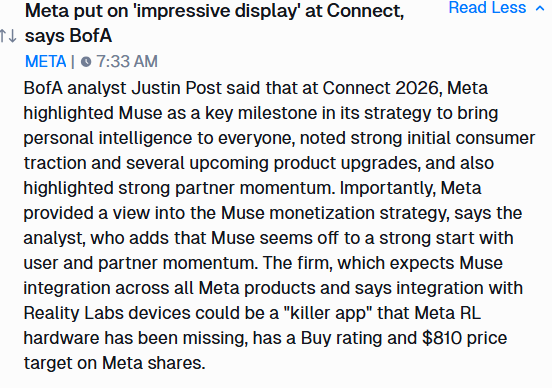
Buy, $831: Bofa said Meta put on “impressive display” at Connect
-
Overweight, $775: Morgan Stanley sees Meta prioritizing Muse adoption and commerce scale over near-term transaction revenue. It expects Meta to enter a partnership with Amazon soon given Walmart’s partnership.
I=4
Buy, $875: Jefferies said industry leaders reinforced its view that Muse is a surprising killer product and personal agents represent a massive consumer and enterprise opportunity. Jefferies said its usage continues to rise as Muse handles increasingly complex tasks with impressive effectiveness. It has been surprised by how much responsibility it has entrusted Muse in just a couple of weeks.
I=4
Buy, $810: Bofa analyst Justin Post said the launch of Meta Enterprise AI solutions could introduce a more durable, less macro-sensitive monetization revenue stream for Meta. He pointed out that the enterprise AI solutions market, including cloud capacity, is expected to exceed $1 trillion by 2028.
I=5
Evercore said digital spending on Meta is currently tracking strongly, thanks to improving returns and performance-driven market share gains. Evercore cited interviews with advertising agency executives overseeing client budgets ranging from more than $10 million to over $3 billion across performance and brand advertising. The firm added that Meta’s Business Agents feature shows encouraging but early signs of potential growth.
I=5
Deutsche Bank said its advertising channel checks are most positive for Meta, thanks to better campaign performance, a more valuable mix of Reels and Stories inventory, accelerating CPMs and growing adoption of its AI tools. It added that digital ad spending improved through Q3 and is tracking better than advertisers initially expected.
One agency reported that Meta’s two-year growth stack accelerated, ending roughly 200 basis points above initial expectations and prompting the agency to raise its Q4 and Q1 forecasts. A second agency check indicated that year-over-year ad spend growth accelerated by approximately 200 basis points through Q3.
Meta’s CPM growth also strengthened, accelerating by roughly 350 basis points sequentially in Q3, following an approximately 650-basis-point acceleration in Q2.
I=4
Buy, $763: Truist sees Meta’s distribution and advertising ecosystem as its key advantage in AI agents, with Muse’s integration across Meta’s massive consumer platforms and SMB tools potentially driving incremental ad spending, even if OpenAI and Google currently have stronger underlying AI reasoning capabilities. It added that Muse is consumer-focused and expanding into small businesses, whereas Dots targets developers and power users.
https://www.investing.com/news/stock-market-news/how-muse-stacks-up-vs-openai-dots-4930890
I=5
Deutsche Bank analyst Benjamin Black said Muse could generate around $8 in annual revenue by 2030
On the lower end of his prediction, Muse could pull in sales of $2.4 billion by 2030.
I=5
Overweight, $796->$1,000: Wells Fargo analyst Ken Gawrelski expects Meta to report Q3 revenue at the high end of company guidance at $64 billion, representing a 25% year-over-year. The firm said time spent on Instagram accelerated around 500 basis points compared to Q2, offset by a 200 basis points decrease at Facebook. It expects Q4 revenue in the range of $72.5- $75.5 billion, representing 21% to 26% year-over-year growth, with the high-end around 3% above consensus estimate.
It expects 2026 operating expense guidance to rise to $175 billion-$177 billion from $165-$169 billion, incorporating the $10 billion teen settlement charge.
It forecasts 2027 operating expenses in the range of $210-$215 billion versus Street estimates of $202 billion.