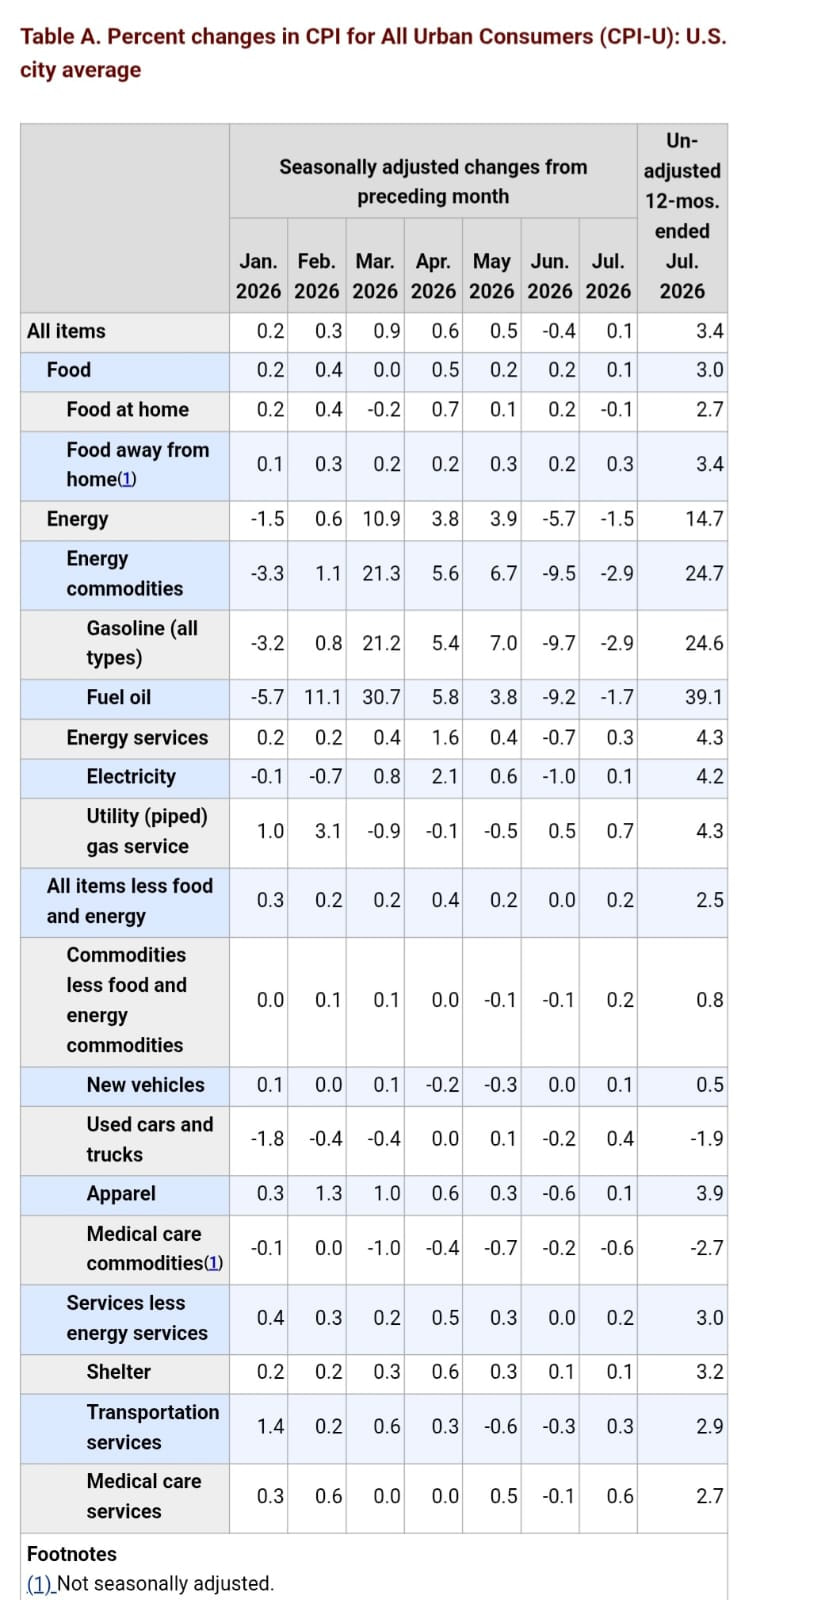
I=7 Core CPI rose 0.2% in December, below 0.3% estimate
Headline CPI rose 0.3% in December and 2.7% y/y, both in line with the estimates.
Core CPI rose 0.2% on the month and 2.6% on the year, below the 0.3% and 2.7% estimates, respectively.
Stock futures were little changed following the report.
The December report is seen as more convincing sign that inflation is on a downward path since October and November data were impacted by the government shutdown.
I=7 Headline CPI rose 0.2% in January, below 0.3% estimate while Core CPI came as expected at 0.3%
Headline CPI rose 0.2% in January versus expectations to stay steady at 0.3%.
On a yearly basis, headline CPI rose 2.4% y/y versus 2.5% estimate and down from 2.7% in December.
Core CPI rose 0.3%, in line with estimate but up from +0.2% in December.
Core CPI rose 2.5% y/y, in line with estimate and down from 2.6% in December.
Stock futures were little changed following the inflation report.
The increase in inflation came from higher prices for airline fares, personal care, recreation, medical care and communication while the decrease in inflation came from used cars and trucks, household furnishings and auto insurance.
I=7 CPI rose 0.3% in February, in line with estimates
CPI rose 0.3% in February, in line with estimates but up from 0.2% in January.
Core CPI rose 0.2% on the month, in line with estimates but down from 0.3% in January.
On a yearly basis, CPI rose 2.4% while core CPI rose 2.5%, both in line with estimates and unchanged from January.
Supercore services inflation, which strips out housing costs, rose 0.35% on the month versus 0.59% in January.
With the Iran conflict threatening to cause a rise in fuel costs and prices of fertilizers, the CPI report may have less influence on the fed’s decision next week.
I=7 CPI rose 0.9% in March, in line with the estimate while core CPI was below estimate
CPI rose 0.9% in March, in line with the estimate but up from 0.3% in February- driven by energy prices, which rose 10.9% in March versus 0.6% in February.
Core CPI rose 0.2% on the month, below 0.3% estimate.
On a yearly basus, CPI rose 3.3% versus 3.4% estimate while core CPI rose 2.6% versus 2.7% forecast.
Stock futures are slightly up following the report, with S&P 500 up 0.15% while Nasdaq 100 futures is up 0.25%.
I=7 Headline CPI met estimates in April, while core CPI came in 0.1 percentage point above forecast
CPI rose 0.6%, in line with estimate and down from 0.9% in March.
Core CPI rose 0.4%, above 0.3% estimate and up from 0.2% in March.
On a yearly basis, CPI rose 3.8% versus 3.7% estimate while core CPI rose 2.8% versus 2.7% estimate..
Shelter rose 0.6%, versus 0.3% in March but is said to reflect a skew of the data due to government shutdown last year.
S&P 500 futures and Nasdaq 100 futures are down 0.3% and 0.7%, respectively but are also likely driven by negative commentary from President Trump regarding the peace deal.
Overall, economists commentaries indicate the report wasn’t that bad but points to stubborn inflation.
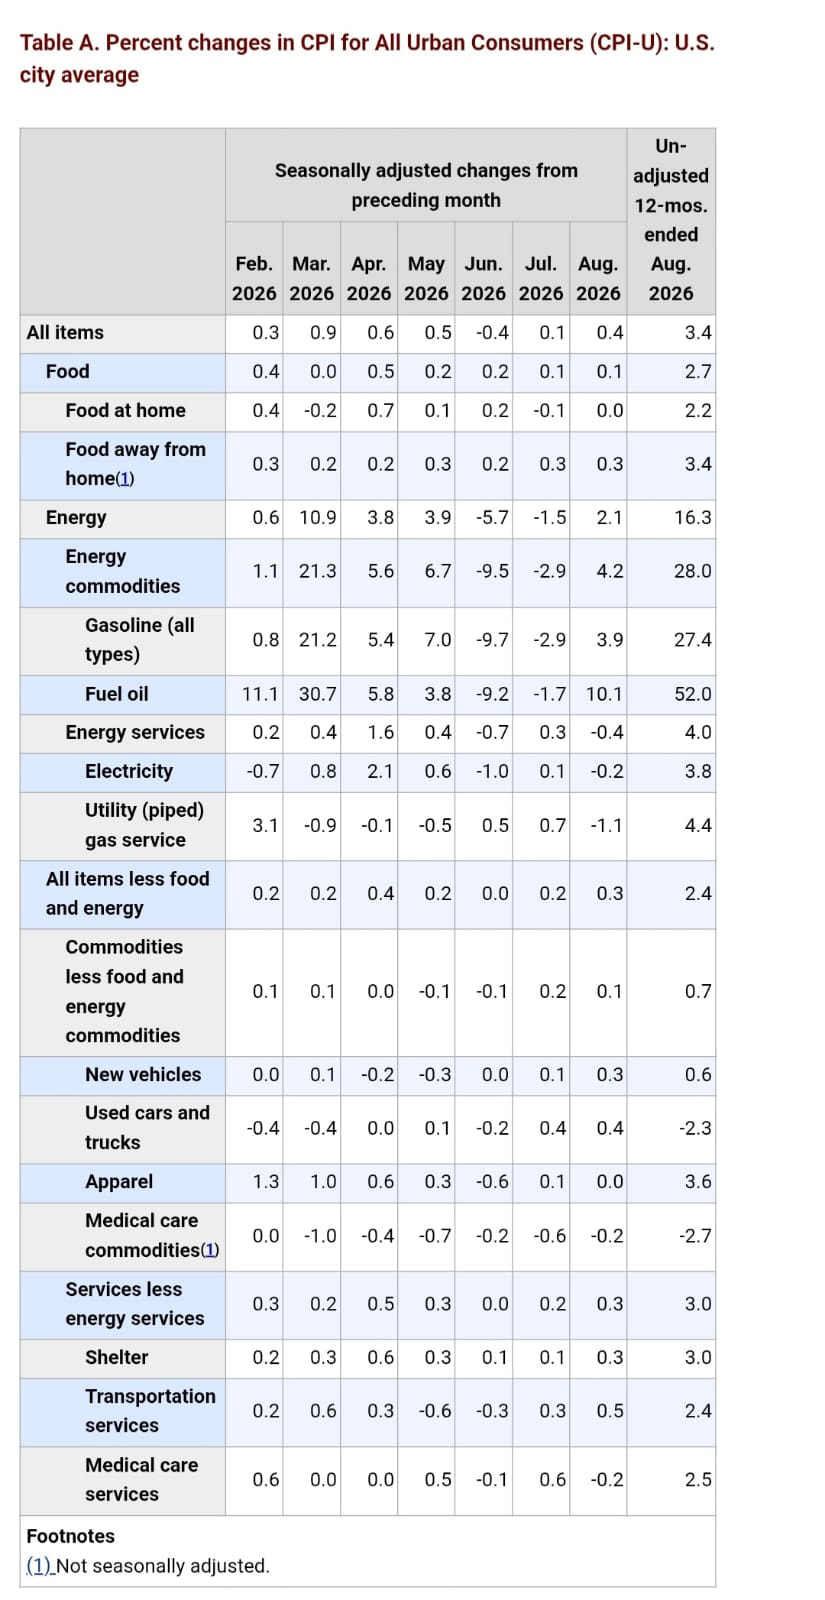
I=8 CPI rose 0.4% in August, in line with forecast but core CPI was above estimate
CPI rose 0.4% in August and 3.4% on a yearly basis, in line with the forecasts.
Core CPI rose 0.3%, above 0.2% estimate- raising the likelihood that the fed will hike interest rates next week.
On a yearly basis, core CPI rose 2.4%, in line with the forecast but down from 2.5% in July.
S&P 500 futures rose 0.5% while Nasdaq 100 futures gained 0.8% following the report.
Fed Chair Kevin Warsh said last month that the Fed would need to take action if it could not be confident that underlying inflation was clearly moving toward its target at a sufficient pace.