This topic covers Sixt’s Q2 2026 earnings. A preview of the results will be posted here ahead of the earnings release. A full summary of the preview is available in the Notion:
Earnings date: August 13, 2026
Time of Earnings release: 7:30 CET
Time of Analysts Call: Unknown
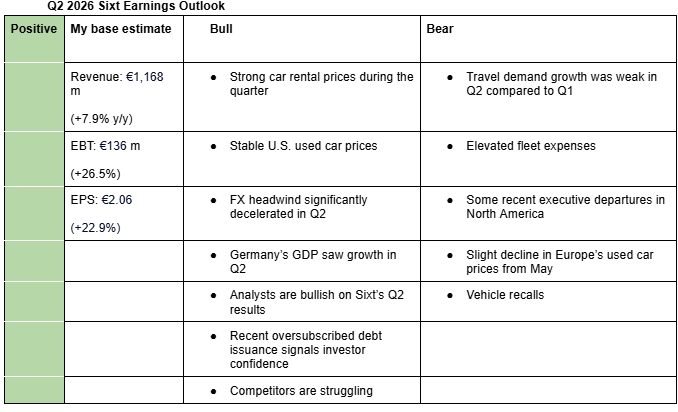
I am positive on Sixt’s Q2 2026 earnings. My estimates (Sixt’s Valuation Model (Google Sheets)) take into account strong pricing, some weakness in travel demand, stable used-car prices, stronger execution relative to competitors, and weaker FX headwind.
Bullish arguments
Strong car rental car prices during the quarter: Hertz reported revenue per day (RPD) growth of 9% y/y for Q2 2026. Avis also reported RPD (excluding rental mix, impacting pricing) of 3% y/y. Hertz added that the industry pricing envirionment continues to be supportive (Q2 2026 Sixt Earnings (Notion)).
Stable U.S. used car prices: Both Avis and Hertz pointed out that the weakness seen in U.S. used car prices in April is seasonal and temporary, adding that the market is doing well (Q2 2026 Sixt Earnings).
FX headwind significantly decelerated in Q2: I estimate that Sixt’s FX headwind was around 2% during the quarter, down from 11.1% in Q1 2026 (Sixt’s FX Impact (Google Sheets)).
Germany’s GDP saw growth in Q2: Germany’s GDP grew by 0.2% q/q, versus -0.2% in Q2 2025 (forum post).
Analysts are bullish on Sixt’s Q2 2026 results: Analysts from Deutsche Bank, DZ Bank, Jefferies, and Berenberg, expect Sixt to report solid results for Q2 2026 (Q2 2026 Sixt Earnings (Notion)).
Recent oversubscribed debt issuance signals investor confidence: Sixt recently issued EUR 500 million bond, which was 3x oversubscribed, signaling investor confidence in the company (forum post).
Competitors are struggling: Sixt’s competitors such as Europcar and Avis continue to struggle, giving Sixt a chance to gain more market share.
Bearish arguments
Travel demand growth was weak in Q2 compared to Q1: According to the International Air Transport Association (IATA), inbound travel demand in Europe rose by an average of 1.4% in Q2, versus 6.1% in Q1. Inbound travel demand in North America fell by an average of 1.1%, versus growth of 2.3% in Q1 (Google Sheets). Avis also flagged this weakness (Q2 2026 Sixt Earnings (Notion)).
Elavated fleet expenses: This is currently one of the main headwinds facing Sixt. Fleet expenses are rising faster than revenue growth due to high maintenance, repair, and reconditioning costs. For instance, fleet expenses rose 19.3% y/y in Q1 2026 versus revenue growth of 8.3% (Valuation Model (Google Sheets)). While Sixt is actively addressing the issue, a near-term resolution is unlikely.
Some recent executive departures in North America: Some Sixt’s North America executives recently left the company. While I didn’t find reports giving reasons for the departures, it may have to do with recent underperformance of North America business in recent quarters (forum post).
Slight decline in Europe’s used-car prices from May: Europe’s used car prices fell 2.2% y/y in June and 0.5% y/y in May. However, this may have little impact on Sixt’s depreciation per unit (DPU) given that more than 98% of its vehicles in Europe are covered by repurchase agreements.
Vehicle recalls: Vehicle recalls remain an industry tailwind. Avis and Hertz each reported an EBITDA headwind of more than $25 million in Q2 related to vehicle recalls (Q2 2026 Sixt Earnings (Notion)).
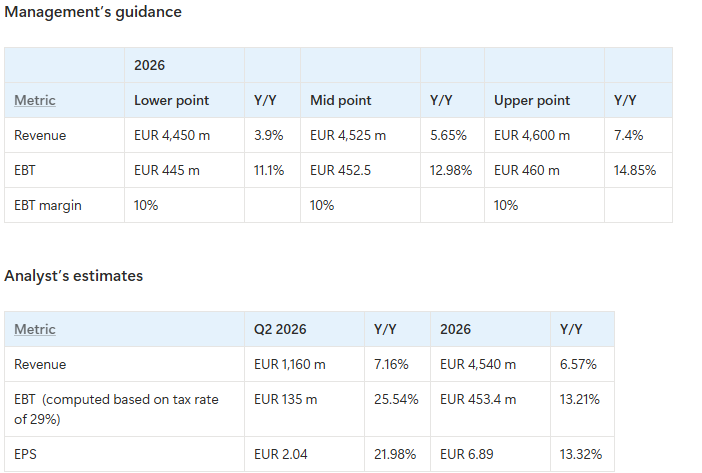
Here are management guidance and analysts’ estimates for Q2 2026 and FY2026:
I=10 Sixt beats revenue expectations but misses EBT expectations due to higher depreciation
Sixt’s Q2 2026 revenue rose 9.9% y/y to EUR 1,189 million, above my estimate of EUR 1,168 million, while EBT rose 14.6% y/y to EUR 123 million, below my estimate of EUR 136 million.
The EBT miss was mainly driven by depreciation and amortization, which came in EUR 29 million above expectations.
Sixt reaffirmed its 2026 guidance, expecting revenue to grow by 4% to 7.5% y/y to €4,450-4,600 m (midpoint: €4,525 m) and EBT margin of around 10% versus my base revenue estimate of €4,597 and EBT of €456.
Sixt revenue from Germany rose 9.1% y/y to €319 m (estimate: €315 m or +7.8%), revenue from Europe rose 13% to €515 m (estimate: 501 m or +9.7%), revenue from North America rose 6.3% to €356 m (estimate: €353 m or +5.5%).
Fleet expenses, which has been one of the main problems, rose 17.1% y/y to €297 m, lower than my estimate of €305 m.
According to Yahoo Finance, Sixt’s results exceeded the average expectations of analysts surveyed by Bloomberg.
The higher-than-expected depreciation and amortization expenses were driven by North America and Europe (excluding Germany). North America depreciation of rental vehicles rose 13.6% y/y to €53 m (Q1 2026: -29% y/y) while Europe (excluding Germany) depreciation of rental vehicles rose 12.4% y/y to €75 m (Q1 2026: +0.9% y/y). While Avis and Hertz pointed out that the weakness in North America used-car prices during the quarter was temporary and seasonal, the higher-than expected depreciation of rental vehicles in Europe (excluding Germany) is concerning, especially since Sixt has a low percentage of risk vehicles in the region.
I=5 Analysts praised Sixt’s Q2 results, saying they exceeded estimates
Buy, €110: Jefferies said Sixt delivered a “solid Q2, beating across the board despite the difficult macro.” It pointed out that revenue and EBT exceeded their expectations of €1.16 billion and €115.3 million, respectively.
Buy, €89: Deutsche Bank said Sixt’s profitability is improving.
Buy, €83: UBS analyst Zehua Jiang said the decision to maintain the full-year outlook despite unexpectedly strong quarterly results reflects prudence in light of ongoing uncertainties rather than a decline in confidence in the second half of the year.
Buy, €90: DZ Bank analyst Dirk Schlamp praised Sixt’s Q2 2026 results, saying they exceeded average estimates. He doesn’t expect any major changes to full-year consensus estimates due to unchanged annual targets.